Your home is likely your biggest investment, but are you financially prepared when things go wrong? Unexpected repairs are a when, not an if, yet in the Federal Reserve's 2024 Survey of Household Economics and Decisionmaking, only 63% of adults said they would cover a hypothetical $400 emergency expense using cash or its equivalent. This guide will help you calculate exactly how much you need, what to prepare for, and how to build your fund strategically.
The short answer: keep 1% to 3% of your home's value in a fund for repairs, on top of your regular emergency savings. Use 1% for a home up to 10 years old, 2% for one 11 to 30 years old, and 3% for one over 30. On a $400,000 home that is $4,000, $8,000, or $12,000. Add more for a pool, septic system, or well, and make sure the total covers your insurance deductible.
| Home value | Up to 10 years old (1%) | 11 to 30 years old (2%) | Over 30 years old (3%) |
|---|---|---|---|
| $250,000 | $2,500 | $5,000 | $7,500 |
| $400,000 | $4,000 | $8,000 | $12,000 |
| $600,000 | $6,000 | $12,000 | $18,000 |
| $800,000 | $8,000 | $16,000 | $24,000 |
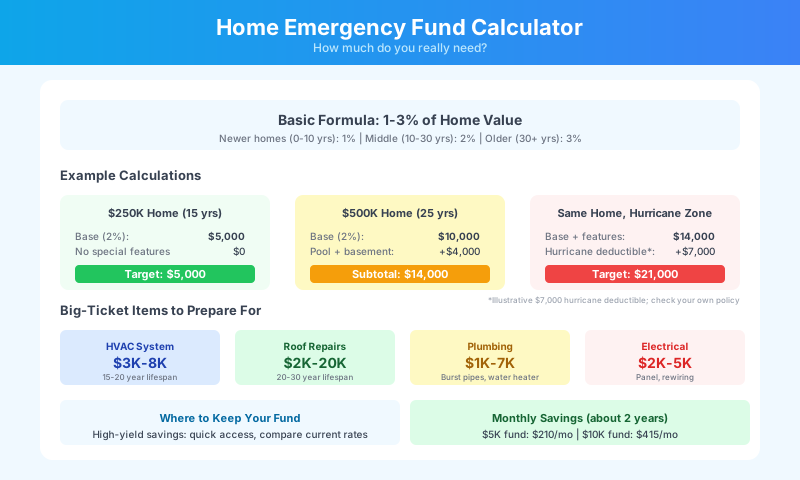
For a figure built from your own home's age, features, and location, use the home emergency fund calculator.
Why Your Home Emergency Fund is Non-Negotiable
Unlike renters who can call their landlord, homeowners are on the hook for everything. Consider these sobering statistics:
- About 1 in 18 insured homes has an insurance claim each year (5.3% of insured homes in 2023), according to the Insurance Information Institute
- Water damage and freezing claims averaged $15,400 per claim over 2019-2023 (Insurance Information Institute)
- 37% of adults would not cover a $400 emergency expense with cash or its equivalent (Federal Reserve, 2024 data)
- HVAC failures tend to happen during extreme weather, when contractors are busiest
Without an emergency fund, you're one broken furnace away from credit card debt or worse—deferred maintenance that compounds into bigger problems.
Calculating Your Magic Number
The Basic Formula
These percentages are common rules of thumb, not data. Adjust them for your home's age, condition and insurance deductibles.
Minimum Emergency Fund = 1% of Home Value
For a $400,000 home: $4,000 minimum
Recommended Fund = 1-3% of Home Value
- Newer homes (0-10 years): 1%
- Middle-aged homes (10-30 years): 2%
- Older homes (30+ years): 3%
Factors That Increase Your Needs
Add a cushion (a rough rule of thumb is a few thousand dollars) if you have:
- Pool or hot tub
- Septic system
- Well water
- Finished basement
- Multiple HVAC systems
- Flat or complex roof
- Trees near structures
Location Adjustments:
- Hurricane, earthquake and flood-prone areas: make sure the fund covers any separate hurricane, windstorm, earthquake or flood deductible in your policies
- Extreme climates: budget extra for heating and cooling repairs, which tend to fail in the worst weather
Real-World Examples
$250,000 Starter Home (15 years old)
- Base fund (2%): $5,000
- No special features: $0
- Moderate climate: $0
- Total needed: $5,000
$500,000 Family Home (25 years old)
- Base fund (2%): $10,000
- Pool and finished basement: +$4,000
- Hurricane zone (illustrative $7,000 hurricane deductible): +$7,000
- Total needed: $21,000
The Big-Ticket Items to Prepare For
HVAC System Failures
Replacement Costs:
- Central AC unit: $3,500-7,500
- Furnace: $3,000-6,000
- Heat pump: $4,000-8,000
- Ductwork: $2,000-5,000
- Furnace and central air replaced together: about $9,200 to $16,200 (HVAC replacement cost calculator)
Warning Signs:
- System 15+ years old
- Frequent repairs
- Rising utility bills
- Uneven heating/cooling
Roof Repairs and Replacement
Cost Ranges:
- Minor repairs: $500-1,500
- Major repairs: $2,000-5,000
- Full replacement: about $11,100 to $22,900 for architectural shingles on a typical house (roof replacement cost calculator)
- Emergency tarping: $200-500
Lifespan by Material:
- Asphalt shingles: 20-30 years
- Metal: 40-70 years
- Tile: 50-100 years
- Wood: 25-30 years
Plumbing Emergencies
Common Crises:
- Burst pipes: $1,000-4,000
- Water heater failure: $1,500-3,500
- Sewer line backup: $3,000-7,000
- Slab leak: $2,000-6,000
- Whole-house repiping: $4,000-15,000
Electrical Issues
Urgent Repairs:
- Panel replacement: $2,000-4,000
- Rewiring (partial): $2,000-5,000
- Emergency electrician: $200-600/hour
- Fire damage: $10,000+
Foundation Problems
Severity Levels:
- Minor cracks: $500-1,500
- Moderate issues: $5,000-10,000
- Major repairs: $10,000-30,000
- Complete failure: $30,000-70,000
Building Your Fund: Practical Strategies
The Fast Track Method
Year 1 Goal: Save 50% of Target
Monthly Savings Required:
- $5,000 fund: $210/month
- $10,000 fund: $415/month
- $15,000 fund: $625/month
- $20,000 fund: $835/month
Creative Funding Sources
One-Time Boosts
- Tax refund: Deposit all or part of it
- Work bonus: Dedicate half or more
- Garage sale: Sell what you don't need
- Selling unused items: List them online
- Credit card rewards: Redeem as cash into the fund
Ongoing Strategies
- Round-up savings apps
- Utility rebates
- Cashback programs
- Side gig dedicated to the fund
- Cancel unused subscription services
The Graduated Approach
Phase 1 (Months 1-6): Save $1,000
- Covers most service calls
- Provides peace of mind
- Achievable for most budgets
Phase 2 (Months 7-12): Reach $3,000
- Covers most single repairs
- Handles multiple small issues
- Basic protection achieved
Phase 3 (Year 2): Hit full target
- Complete protection
- Can handle major failures
- Sleep soundly
Smart Fund Management
Where to Keep Your Money
High-Yield Savings Account (Recommended)
- Pros: Competitive interest (rates change, so compare current offers), quick access, FDIC insured up to the limit
- Cons: Temptation to spend
- Best for: Primary emergency fund
Money Market Account
- Pros: Higher rates, check writing
- Cons: Minimum balances
- Best for: Larger funds ($10,000+)
Short-Term CDs
- Pros: Higher rates, forced saving
- Cons: Penalties for early withdrawal
- Best for: Excess emergency funds
What to Avoid
- Checking account (no growth)
- Investment accounts (too volatile)
- Long-term CDs (not liquid)
- Under the mattress (seriously?)
The Two-Tier System
Tier 1: Immediate Access ($3,000-5,000)
- High-yield savings
- Covers urgent repairs
- Available within hours
Tier 2: Short-Term Investment (Remainder)
- 3-6 month CDs
- Money market funds
- Slightly higher returns
- 1-3 day access
Using Your Fund Wisely
True Emergencies Only
Qualifies as Emergency:
- Safety hazards
- System failures
- Structural damage
- Water intrusion
- No heat/cooling in extreme weather
NOT Emergencies:
- Cosmetic updates
- Wanted upgrades
- Regular maintenance
- Property tax increases
- Furniture purchases
The Decision Framework
Ask yourself:
- Will waiting cause more damage?
- Does it affect habitability?
- Is it a safety concern?
- Will insurance cover it?
- Can it wait for budgeted funds?
If you answer YES to questions 1-3, use your emergency fund.
Replenishment Strategies
After Using the Fund
Priority #1: Refill to minimum level ASAP
Aggressive Replenishment Plan:
- Pause all non-essential spending
- Take on temporary side work
- Sell unnecessary items
- Use tax refunds/bonuses
- Reduce retirement temporarily (last resort)
Timeline Goals:
- Minor use (under $1,000): Refill in 2-3 months
- Moderate use ($1,000-5,000): Refill in 6 months
- Major use (over $5,000): Refill within 1 year
Beyond the Emergency Fund
The Complete Financial Picture
Your Financial Defense Layers:
- Emergency Fund: First line of defense
- Insurance: Catastrophic protection
- Home Warranty: Appliance/system coverage
- Maintenance Fund: Preventive care
- Credit Access: Absolute last resort
Preventive Maintenance Saves Money
Annual Maintenance Budget: 1% of Home Value (a common rule of thumb)
Separate from emergency fund for:
- HVAC servicing
- Gutter cleaning
- Roof inspections
- Pest control
- Tree trimming
Prevention is usually far cheaper than emergency repairs. A proactive maintenance schedule is what keeps most "emergencies" from ever happening.
Emergency Fund by Life Stage
The targets below are rules of thumb to start from, not research findings.
New Homeowners (Years 1-5)
- Priority: Build fund quickly
- Target: 1.5% of home value
- Focus: Learn your home's needs
Established Homeowners (Years 5-15)
- Priority: Maintain and grow
- Target: 2% of home value
- Focus: Plan for big replacements
Long-Term Owners (15+ Years)
- Priority: Prepare for major systems
- Target: 3% of home value
- Focus: Aging infrastructure
Retirees
- Priority: Avoid fixed income stress
- Target: 3-5% of home value
- Focus: Comfort and safety
Common Mistakes to Avoid
The Pitfalls
- Using fund for upgrades: Granite counters aren't emergencies
- Underestimating needs: Better over than under
- Not replenishing: Creates future vulnerability
- Keeping in checking: Too easy to spend
- Forgetting inflation: Adjust target annually
The Insurance Trap
"I have insurance, why save?"
- Deductibles can run into thousands of dollars
- Many issues aren't covered
- Claims can increase premiums
- Processing takes time
- Coverage limits exist
Example Scenarios
These are illustrative examples, not real households:
- The midsummer AC failure. An air conditioner dies in July. With a funded emergency account, the repair can be scheduled right away instead of waiting or putting it on a high-interest card.
- Storm damage and the deductible. A tree falls on the roof. Insurance covers much of the repair, but the homeowner still owes the deductible and may need temporary repairs before the claim is settled. An emergency fund covers that gap.
- Building from zero. A first-time buyer starts with a few hundred dollars and adds a fixed amount every month. Even a partly funded account means the first surprise repair doesn't go on a credit card.
Where to start
Work out your target with the home emergency fund calculator, open a separate savings account for it, and set an automatic monthly transfer, however small. Reach your insurance deductible first, then the base percentage for your home's age. Money is half of being ready. A home emergency preparedness plan covers the other half: the shutoffs, the contacts, and the documents.